The Bright Man Group — Choose To Prosper

Business Credit Consulting

Build business creditthe correct way.

The Bright Man Group helps owners establish credit under their business entity, become genuinely funding ready, and identify the loans, credit lines and vendor accounts they can qualify for.

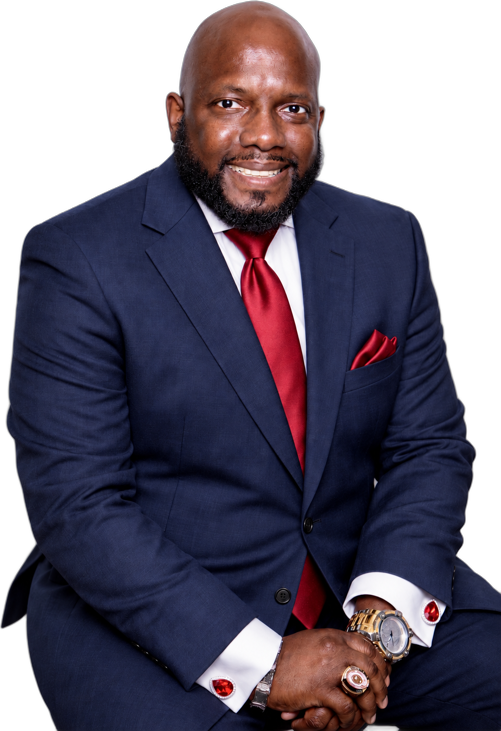
Kenneth Jenkins, founder of The Bright Man Group

Credit in the business’s name

A commercial profile that stands on its own, instead of every application leaning on your personal credit.

Readiness before applications

We close the gaps a lender looks at before anything is submitted, so inquiries are spent on accounts worth having.

A sequence, not a shopping list

You get the specific loans, credit lines and vendor accounts your profile fits, and the order to pursue them in.

Why “the correct way”

Most owners are told they are building business credit. Usually they are building personal credit with a business logo on it.

It looks the same from the outside: applications go out, accounts get opened, credit gets used. But nothing is being reported under the business, so there is no commercial profile forming, and the next lender is still looking at the owner’s personal file to decide.

Building it correctly means starting with the entity, the business information and the commercial bureau files, then adding accounts that actually report there. Done in that order, a business earns access to capital on its own merits — and the owner’s personal credit stops carrying the whole company.

  • Credit established under your legal business entity
  • Accounts chosen because they report to the business bureaus
  • Applications sequenced so each approval helps the next one
Modern office tower lit at dusk

“No guarantees, no shortcuts — just the profile a lender can actually underwrite.”

How we approach every engagement

What we do

Three services, in the order they should happen.

Each one stands on the one before it. Jumping straight to an application without the foundation underneath is what produces denials, and it is the most common mistake we see.

Business Credit Building01Credit building

Business Credit Building

Establish credit in the business's own name, the correct way

We build a business credit profile that is separate from your personal credit, established under your legal business entity and reported to the commercial bureaus.

  • Business entity, address and phone setup review
  • D-U-N-S number and commercial bureau file setup
  • Vendor and tradeline strategy that reports to the business bureaus
See what it covers
Funding Readiness02Funding readiness

Funding Readiness

Know exactly what your business qualifies for before you apply

We pressure-test the numbers, documentation and profile a lender looks at, and close the gaps before an application ever goes out.

  • Revenue, banking and documentation review
  • Profile audit against the criteria lenders actually apply
  • A written readiness plan with the gaps listed in priority order
See what it covers
Loans, Credit Lines & Vendor Accounts03Lender & vendor access

Loans, Credit Lines & Vendor Accounts

A shortlist matched to your profile, not a list of guesses

We identify the loans, revolving credit lines and vendor accounts your business can realistically qualify for, and the order to pursue them in.

  • Matched shortlist of loans, credit lines and charge cards
  • Net-30 and vendor accounts that report to the bureaus
  • Recommended application order and spacing
See what it covers

How it works

Four steps, and the order matters more than the speed.

Credit that a lender will underwrite has to be built deliberately. This is the path we walk with every owner, from the first conversation to the accounts worth applying for.

  1. 1

    Start with a conversation

    We talk through your entity, how long you have been operating, what you have already applied for, and what you actually need the funding to do.

    No cost, no obligation

  2. 2

    Build the business credit foundation

    Your commercial profile gets set up correctly in the business's name: entity details, business contact information, bureau files and the first accounts that report.

    Personal credit stays personal

  3. 3

    Get funding ready

    We review your revenue, banking and documentation against what lenders look for, and close the gaps in priority order before anything is submitted.

    Gaps listed, then closed

  4. 4

    Pursue the right accounts, in the right order

    You get a shortlist of loans, credit lines and vendor accounts matched to your profile, with the order and timing that gives each application the best chance.

    Sequenced, not scattered

Why owners work with us

Straight answers, and none of the promises we cannot keep.

Approval decisions belong to the lenders and vendors. What we control is how well your business is set up before those decisions get made.

More about our approach
01

One conversation first

Before any plan, we want to understand the entity, the history and what the money is actually for.

02

Documented, not implied

You get the gaps written down and prioritised, so you can see what is being worked on and why.

03

Personal credit stays personal

Part of the work is separating the business profile from the owner, deliberately and in the right order.

04

Honest about timing

If the file is not ready, we say so and say what needs to change before an application goes out.

Questions

Straight answers before you commit to anything.

Business credit is established under your legal entity and reported to commercial bureaus, so it is underwritten on the business's own profile rather than on your consumer file. Building it correctly is what lets a business grow its access to capital without leaning on your personal credit every time.

It depends on your starting point: your entity, how long you have been operating, and what is already on your commercial files. We map the timeline for your specific situation after the first conversation rather than quoting a number that may not apply to you.

An entity is part of the foundation, because credit in the business's own name requires a business to attach it to. If you are not registered yet, that becomes the first item on the plan.

Part of the work is separating the two. Vendor and commercial accounts set up in the business's name generally report to the business bureaus, not your consumer file, and we plan the sequence of applications so inquiries are placed deliberately rather than spread around.

No, and you should be cautious with anyone who does. Approval decisions belong to the lenders and vendors, and they depend on your business's own profile. What we control is preparing that profile properly and matching you to accounts you can realistically qualify for.

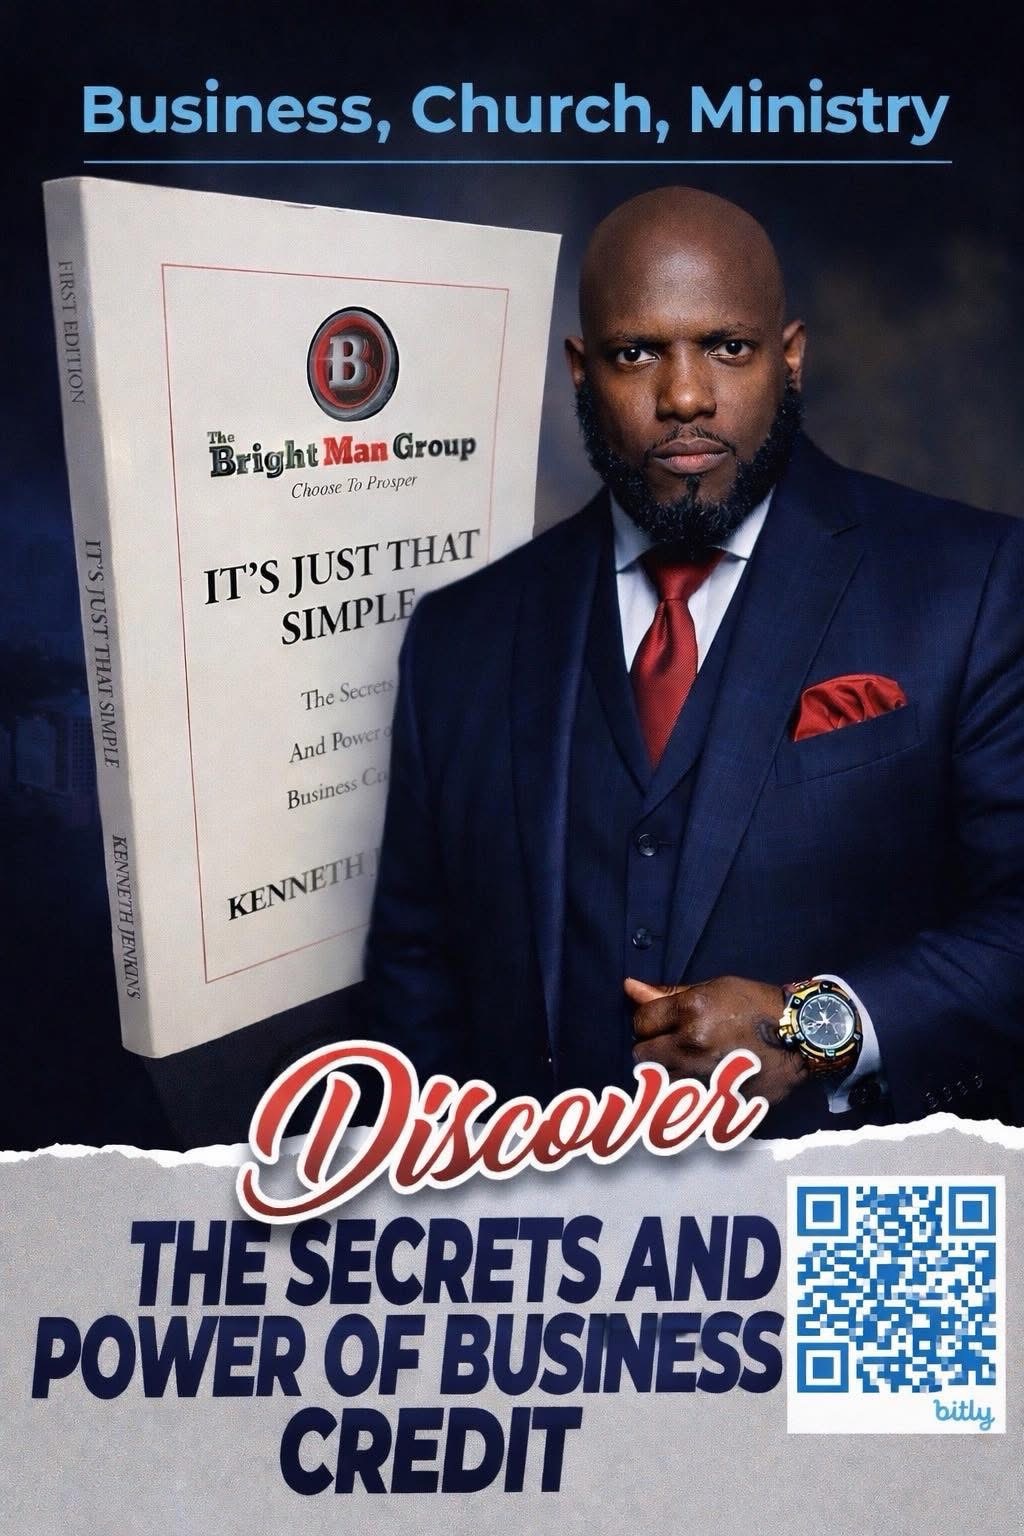
It’s Just That Simple by Kenneth Jenkins — book cover with the author

The book

It’s Just That Simple

By Kenneth Jenkins

Written for owners who want the subject explained plainly, this book walks through the secrets and power of business credit — where a commercial profile actually comes from, what the bureaus look at, and how the pieces fit together for a business.

It is a practical companion to the work we do: read it to understand the foundation before you start building on it, whether you are launching your first company or taking a settled one into its next stage of growth.

  • Business, church and ministry contexts
  • The foundation under a commercial profile
  • How readiness ties to real approvals
  • A plain-language place to start

Purchases are completed on the book’s own secure payment page, which opens in a new tab.

About

About Kenneth

Kenneth Jenkins leads The Bright Man Group, helping business, church and ministry owners build credit with their EIN and get funding ready the right way. He is also the author of It’s Just That Simple, and his motto says it plainly: choose to prosper.

Kenneth Jenkins, founder of The Bright Man Group

Kenneth Jenkins

The Bright Man Group

The program

Business Credit Program

Here is why most business, church and ministry owners fail at building business credit: they start applying for the wrong accounts in the wrong order.

Denials
Accounts that do not report
Slow credit growth
Wasted time

When you follow the correct sequence, the entire process becomes much faster.

Step-by-step course

We put together a complete step-by-step course guided by our reps showing exactly how this works:

We Teach You How to Build Business Credit FAST in 2026Step-by-Step Guide to $100K+ Funding

You’ll learn

  • The first accounts to open when building credit from scratch.
  • How to trigger the credit reporting that generates strong business scores.
  • How to accelerate your path to $100K+ in funding capacity.
  • The exact positioning strategy that gets you approved.

If you want to access more capital without relying on personal credit, this is the roadmap.

Enrollment is completed on the program’s own secure payment page, which opens in a new tab. Prefer to talk it through first? Send an inquiry.

Start here

Let’s find out what your business can qualify for.

Tell us where things stand today and we will come back with a straight read on the foundation, your funding readiness, and the accounts worth pursuing first.

Prefer to read first?
See how the process works or the three services.

No cost, no obligation. We never sell your information.

Before you start

Questions

The question owners ask before almost anything else, answered plainly. If yours is not here, call and ask it.

Call (862) 436-8872

Normally up to 6 months.